
Higher Interest Rates Have You Hitting Pause On Your Home Search? Why Now Could Be a Smart Time for First-Time Buyers
At Revamped Real Estate, some of our most rewarding experiences have been handing over the keys to a first-time home buyer. We work with many first-time home buyers across Chester County, Delaware County, and beyond, and right now we're hearing the same question again and again: "Should I wait until rates come down?"
If rising interest rates have you hitting pause on buying your first home, you're not alone. When rates go up, a lot of buyers decide to sit on the sidelines. But here's what many first-time buyers don't realize: that pause can open real doors for the buyers who are ready to move forward.
Below, we'll break down what today's market means for you, what the local numbers actually say, and the loan programs that can make buying your first home more doable than you might think.
What Higher Rates Can Mean for You
Less competition. When fewer buyers are actively shopping, you'll see fewer bidding wars and fewer buyers offering well over asking price. That means your offer has a better chance of standing on its own.
More room to negotiate. Sellers are more open to helping close the deal. That could mean covering some of your closing costs, paying for a rate buydown to lower your monthly payment, or handling repairs before you move in.
Your protections are back. In a competitive market, buyers often feel pressure to waive their inspections and financing contingencies just to get noticed. With less competition, this is not as necessary.
Time to decide on your dream home. No more making a huge decision after one 15-minute showing out of fear someone else will beat you to it. You can take a second look, ask questions, and feel more confident about your choice before you submit your offer.
What the Local Numbers Say
National headlines don't tell the whole story, because real estate is local. In the broader Philadelphia–Camden–Wilmington metro, active listings were up 13.3% year over year in August, compared to just 3.6% nationally. Homes were spending about 48 days on the market, and price reductions were on the rise. More inventory and more time on market generally mean more options and more negotiating power for buyers. (Realtor.com)
At the same time, Redfin recently named Montgomery, Chester, and Bucks Counties one of only five seller's markets among the 49 large U.S. markets it analyzed, with buyers still outnumbering sellers. In other words, desirable homes in our area are still in demand. What does that mean for you? Conditions can look very different from one town, price point, or neighborhood to the next. That's exactly why it helps to work with a local team who knows where the opportunities are and how to write an offer that wins.
Loan Options Built for First-Time Buyers
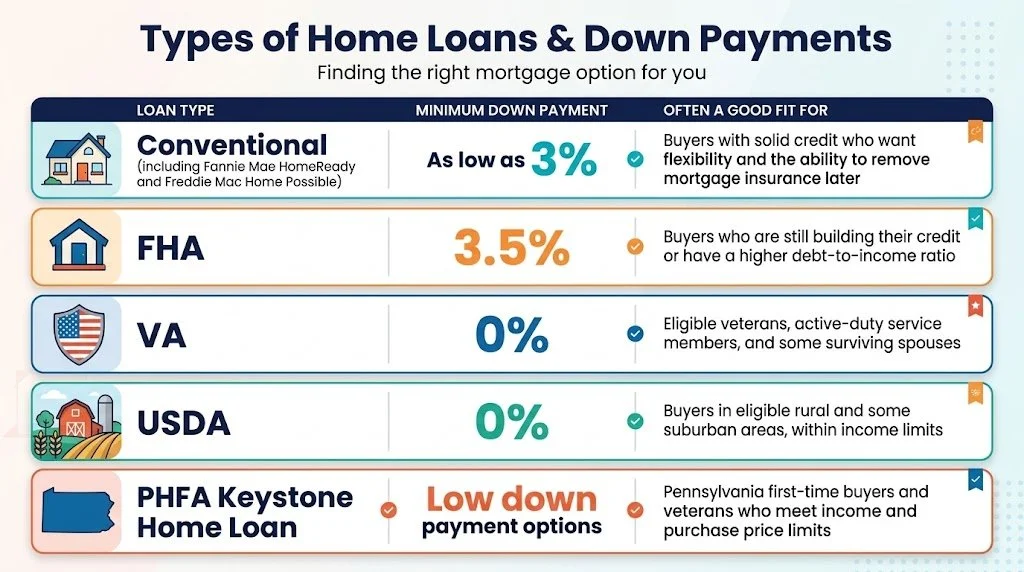
Conventional loans are the most common mortgage. With low-down-payment options starting at 3%, they're often a great fit if your credit is in good shape. Private mortgage insurance (PMI) is typically required with less than 20% down, but it can usually be removed once you build enough equity.
FHA loans are backed by the federal government and have more flexible credit requirements, making them a popular choice for first-time buyers. They do carry mortgage insurance, which is worth comparing with a conventional loan.
VA loans are one of the best benefits available to those who have served in the military. They allow eligible buyers to purchase with no down payment and no monthly mortgage insurance.
USDA loans offer no-money-down financing in eligible areas. Some parts of our region, including areas of Chester and Berks Counties, may qualify, so it's worth checking an address before you rule it out.
Pennsylvania Programs That Help With Down Payment and Closing Costs
The Pennsylvania Housing Finance Agency (PHFA) offers first mortgages with competitive rates, plus assistance that can be layered on top:
K-FIT (Keystone Forgivable in Ten Years): A second loan of up to 5% of the purchase price toward your down payment and closing costs, with no monthly payment. It's gradually forgiven over 10 years as long as you stay in the home.
Keystone Advantage Assistance Loan: Up to 4% of the purchase price or $6,000 (whichever is less) as a 0% interest second loan, repaid over 10 years.
These programs have income limits, purchase price limits, credit score minimums, and a homebuyer education requirement, and they must be used with a PHFA-participating lender. You can't combine K-FIT and Keystone Advantage on the same purchase, so your lender will help you choose the right fit.
The right loan depends on your credit, savings, income, and where you want to live. That's why we connect every buyer with a trusted local lender early in the process.
What If Rates Drop Later?
No one can promise where interest rates will go. But if they come down in the future, refinancing could be an option. The price you negotiate today, however, is yours to keep.Our own Eric Dabundo recently bought his home in West Chester in this same market, using lower buyer competition and creative offer terms to offset higher rates. We know this strategy works because we've lived it. Ready to Take the Next Step?
Whether you're ready to start touring homes or just want to understand your options, Revamped Real Estate is here to help. We'll walk you through which loans and programs you might qualify for, connect you with a trusted lender, and help you build a plan that fits your budget.
Contact us today to schedule your free first-time buyer consultation.